Tuesday, April 4, 2023

Teck rejects unsolicited $23bn takeover bid from Glencore

Teck rejects unsolicited takeover bid from Glencore  

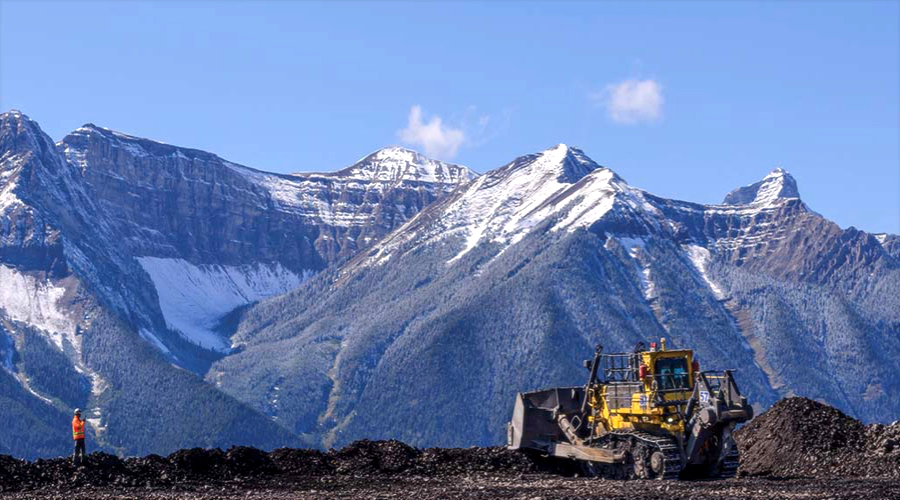
Teck’s Greenhills steelmaking coal operation in Elk Valley, British Columbia. (Image courtesy of Teck Resources.)

https://www.mining.com/teck-rejects-unsolicited-takeover-bid-from-glencore/ 

Teck Resources (TSX: TECK.A, TECK.B) (NYSE: TECK), Canada’s largest diversified miner, has rejected an unsolicited acquisition proposal from Swiss commodity trader and mining company Glencore Plc (LON: GLEN).

The all-share acquisition bid contemplated Glencore offering 7.78 shares for each Teck Class B subordinate voting share, and 12.73 Glencore shares for each Teck Class A common share. The proposal represented a 20% premium as of March 26, according to Teck, and would be worth about $23.2 billion at Friday’s closing prices.

The board’s decision, Teck said, was unanimous. It noted that Glencore’s bid was to acquire the company and subsequently create two units, which would expose Teck shareholders to a large thermal coal and oil trading business.

The Vancouver-based company said a merger would increase geopolitical risk for its shareholders, given Glencore’s presence in jurisdictions such as the Democratic Republic of Congo (DRC), and the inclusion of oil trading in the metals unit would undermine its appeal to investors.

“[All of this] would negatively impact the value potential of Teck’s business, is contrary to our ESG commitments and would transfer significant value to Glencore at the expense of Teck shareholders,” chief executive, Jonathan Price, said in the statement.

Teck announced in February it was switching its name to Teck Metals Corp. and spinning off its multibillion-dollar steelmaking coal unit into a new company — Elk Valley Resources Ltd.

Teck had been weighing options for its metallurgical coal division for over a year, as the commodity is used in steelmaking, one of the most polluting industries.

“The proposed separation into Teck Metals and Elk Valley Resources is in the best interest of Teck and all its stakeholders,” the company said on Monday.

“The board is not contemplating a sale of the company at this time,” chair Sheila Murray said.

The miner’s controlling Keevil family said through Norman Keevil, who holds the role of chairman emeritus, that now was “not the time to explore a transaction of this nature.”

Teck is instead urging shareholders to approve the separation of Teck Metals and Elk Valley Resources at an April 26 meeting.

The two companies had discussed a potential merging in 2020, but those talks did not advance, according to documents both companies published Monday.

Eyes on copper

Experts had anticipated that the company’s decision to split the business in two would make Teck Metals a takeover target. The company owns four copper mines in South America and Canada, which produced 270,000 tonnes combined last year. 

Teck also expects to double copper output after the second phase of its Quebrada Blanca project in Chile ramps up to full capacity by the end of 2023.

Top miners, in turn, are hungry for copper assets as demand for the metal accelerates and a global shortfall looms. BHP, Rio Tinto and Glencore itself have disclosed that they are actively looking to grow their copper exposure.
Teck rejects unsolicited $23bn takeover bid from Glencore
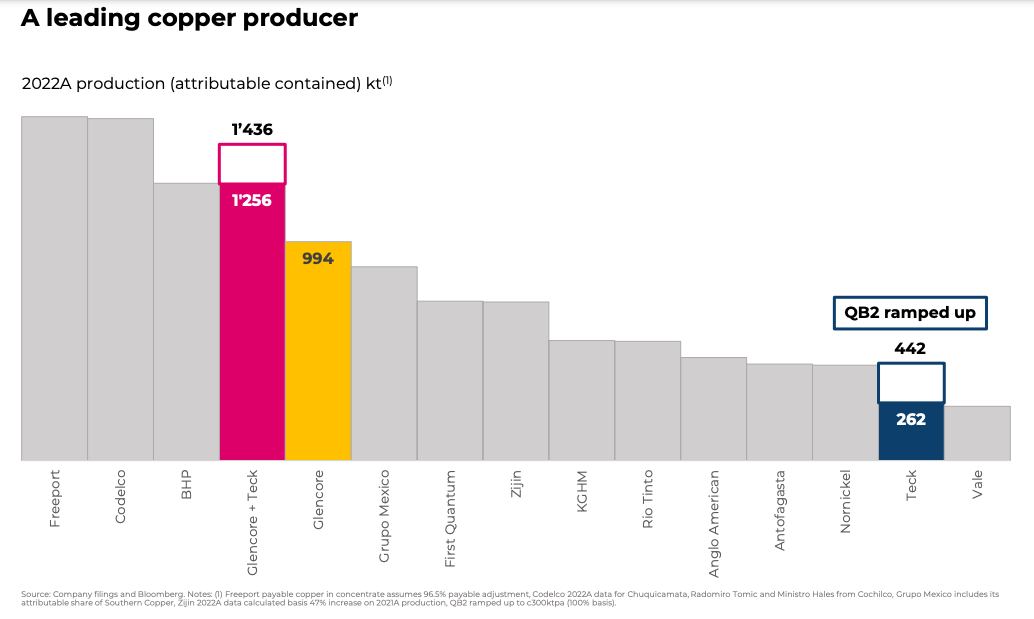
Glencore’s potential acquisition of and Teck would create two larger and more diversified companies than Teck’s own spinout plans. (Image courtesy of Glencore’s proposal presentation.)

The main difficulty for any potential suitor for Teck’s copper assets will be the new structure, post-breakup, which funnels royalties from a separated coal business to the base metals operations, as well as a six-year phase-out of a dual-class share structure, under which Canada’s Keevil family currently controls the company.

“Adding Teck Metals would position any major miner as a dominant player in base metals,” Citi analyst Alexander Hacking said in a February note to investors. “That said, six years can be a long time in equity markets and a lot could change between now and then.”

US-listed shares of Teck rose more than 11% to $40.52 each in pre-market trading and were last trading at $42.87 each. Glencore’s shares were down on Monday afternoon almost 2.7% to 451.25p, but recovered later to close 1.15% higher at almost 470p.

For Glencore, acquiring Teck would be its biggest acquisition since buying Xstrata Plc in 2012 and it would “unlock approximately $4.25 billion — $5.25 billion of post-tax synergy value”, it said in a letter.

The Swiss company noted that its proposed acquisition would create two larger and more diversified companies than Teck’s own spinout plans.

It also highlighted that the combined metals-mining company would be headquartered in Canada, adding its coal business would stick to its plans to exit thermal coal by 2050.

Sweeter offer to come

Several mining experts are already predicting that Glencore won’t give up on Teck easily. Analysts at both the Royal Bank of Canada and Jefferies Group said the UK mining and commodities giant will likely raise its bid to win over Teck shareholders and the Keevil family.

Jefferies analyst Christopher LaFemina said in a note that while Glencore’s proposal is “compelling on paper,” a higher price and/or “cash kicker” is clearly needed. An improved offer is likely, he said, though “it is not clear that a modestly higher price is all that is necessary.”

RBC analysts led by Tyler Broda called the offer “relatively modest” that “potentially leaves room for Glencore to return.”

So far Glencore seems undaunted by Teck’s rebuffal. A few hours after the Canadian miner’s rejection Glencore chief executive officer, Gary Nagle, and other company executives held a conference call highlighting the virtues of the deal to investors and analysts. The tone suggested the potential acquisition is still on the cards, with Nagle describing Teck’s objections as “not real issues.”

Monday, April 3, 2023

Kilmeade: The world is on fire

“Americans Will Be Poor Overnight!” - Reaction To China & Brazil Agreeme...

Banks Brave Junk Debt Jitters With $3.8 Billion Citrix Bond Sale

Reuters

FILE PHOTO: Citrix Systems logo is seen on smartphone placed on U.S. Dollars in this illustration taken, January 31, 2022. REUTERS/Dado Ruvic/Illustration/File PhotoReuters

https://money.usnews.com/investing/news/articles/2023-04-03/banks-brave-junk-debt-jitters-with-3-8-billion-citrix-bond-sale

By Matt Tracy and Abigail Summerville

WASHINGTON (Reuters) - A Goldman Sachs Group Inc-led group of banks will hold an investor call on Monday to sell $3.8 billion in Citrix Systems bonds, according to two sources familiar with the matter, in a sign that the market for junk debt that was roiled by last month's banking crisis is starting to thaw.

It is by far the biggest junk debt sale since the failures last month of U.S. regional banks Silicon Valley Bank and Signature Bank and the forced sale of Credit Suisse Group AG to Swiss peer UBS Group AG.

Issuance of junk bonds in the U.S. dropped from $13.9 billion in February to $4.45 billion in March, according to Informa, as the market turmoil soured risk appetite.

"The leveraged finance market has been incredibly quiet this year," said Tim Leary, senior portfolio manager at BlueBay Asset Management.

The new Citrix bonds will refinance most of a $3.95 billion unsecured bridge loan that helped private equity firms Vista Equity and Evergreen Coast Capital acquire the cloud software maker for $16.5 billion in September 2022. The loan would have matured in September 2023.

The banks will hold a call with investors in the afternoon on Monday and stage presentations for them through Tuesday.

The 6.5-year notes are being marketed with a 9% coupon and will be non-callable through September 2025, according to one of the sources.

In addition to Goldman Sachs, the 33-bank arranger group includes Bank of America, Credit Suisse, Barclays, Citibank and Deutsche Bank.

Citrix, Vista, Evergreen and Goldman Sachs declined to comment.

The banks were able to sell $8.55 billion of the Citrix buyout debt to investors by September last year, realizing roughly $600 million in losses as investors demanded steep discounts in the wake of a rapid rise in interest rates. Several block trades of the remaining debt have since then taken place.

In addition to Citrix, banks are expected to market to investors a portion of the $5.4 billion in debt which last year financed auto parts supplier Tenneco's buyout by Apollo Global Management.

(Reporting by Matt Tracy and Abigail Summerville in New York; Editing by Josie Kao)

Trump Arrives in New York City Ahead of Tuesday’s Arraignment

 Former US President Donald Trump waves as he arrives at Trump Tower in New York on April 3, 2023.  (ED JONES/AFP via Getty Images)

Former US President Donald Trump waves as he arrives at Trump Tower in New York on April 3, 2023. (ED JONES/AFP via Getty Images)

https://www.theepochtimes.com/trump-arrives-in-new-york-city-ahead-of-tuesdays-arraignment_5168926.html 

Former President Donald Trump arrived in New York City on Monday afternoon as he prepares to surrender himself to the Manhattan District Attorney after a grand jury indicted him last week.

Live stream footage showed Trump’s private Boeing 737 jet arriving at La Guardia Airport in Queens, New York. At around 3:45 p.m. ET, Trump was seen departing the plane and traveling away from the airport in a black motorcade.

At the Trump Tower, an Epoch Times reporter said that a crowd of pro-Trump protesters called the indictment a sham and called on President Joe Biden to be fired. Trump later entered the Trump Tower at around 4:25 p.m. ET as three black helicopters were seen overhead.

“If you are doing poorly, as so many of you are, do not send anything,” Trump wrote on Truth Social at around 3:30 p.m. as his plane landed in New York. “If you are doing well, which was made possible through the great policies of the Trump Administration, send your contribution … we have to take back our Country and, MAKE AMERICA GREAT AGAIN!”

Security was increased in and around Manhattan ahead of his arraignment, set for Tuesday. The New York Police Department has closed roads around the city, officials said earlier on Monday in a news conference.

Trump, a native of Queens, still holds property in New York City and said he will stay at his Trump Tower on Fifth Avenue in Manhattan. Security around the Trump Tower was also bolstered.

“There has been no specific credible threats to our city at this time, and New Yorkers should go on with their regular activities,” New York City Mayor Eric Adams said at a news conference.

Epoch Times Photo
Members of the media wait outside Trump Tower as former President Donald Trump is expected to arrive after his indictment by a Manhattan grand jury in New York City on April 3, 2023. (Carlos Barria/Reuters)

Before heading to New York City, Trump rode in motorcade from his Mar-a-Lago club to his Boeing 757, which was carried live on cable and local television. It took him past supporters waving banners and cheering, while decrying the case against him as politically motivated.

Cable networks followed his plane at airports in Florida and New York with video from the air, and Trump was joined aboard by a small group of senior campaign aides as well as his son, Eric Trump, who posted photos of the wall-to-wall TV coverage from his seat.

Trump is reportedly facing multiple charges of allegedly falsifying business records in the indictment handed down by a Manhattan grand jury last week. The investigation is scrutinizing six-figure payments made to Stormy Daniels, although the indictment has not yet been unsealed.

It’s an unprecedented chapter in American history, with Trump the first former president to face criminal charges. But he has said it could actually boost his chances of winning the presidency again next year and has made the indictment a central theme of his 2024 campaign.

Trump senior adviser Jason Miller said the campaign had raised $7 million since word of the indictment broke, but official figures have not yet been released. One Trump fundraising email Monday carried the subject line, “Tomorrow, I will be arrested.”

Epoch Times Photo
Former President Donald Trump arrives at Trump Tower on Fifth Avenue in New York City on April 3, 2023. (Drew Angerer/Getty Images)

Trump’s attorney said on Sunday he expects to make a motion to dismiss any charges stemming from Manhattan district attorney Alvin Bragg’s investigation.

“We will take the indictment. We will dissect it. The team will look at every, every potential issue that we will be able to challenge, and we will challenge. And of course, I very much anticipate a motion to dismiss coming because there’s no law that fits this,” Tacopina told CNN on Sunday.

Tacopina then described the case as politically motivated and said it would never had been brought if it didn’t involve Trump.

“And you have a situation where, you know, the federal government, the Department of Justice, turned this matter down,” Tacopina told the outlet. “The FEC, which governs federal election laws, said there’s no violation here.” But, he added, that “somehow, a state prosecutor has taken a misdemeanor and tried cobble together to make it a felony by alleging a violation of federal campaign violations … the FEC said that doesn’t exist.”

On Monday, Trump attorney Alina Habba, who is representing the former president in the classified documents case, told CNN that she opposes the release of his mugshot. It should remain confidential because he’s running for president, she argued.

“I like transparency. I think that in certain situations, it’s a good thing. I do have a problem with leaking of pictures,” Habba remarked. “I think that because we’re in a campaign because he’s the leading GOP candidate, it’s not going to help anything.”

Eva Fu and The Associated Press contributed to this report. This is a developing story; check back for more updates.

America’s Biggest Banks Experience Massive Deposit Withdrawals

Silicon Valley Bank customers wait in line at SVB headquarters in Santa Clara, Calif., on March 13, 2023. (Noah Berger/AFP via Getty Images)

Silicon Valley Bank customers wait in line at SVB headquarters in Santa Clara, Calif., on March 13, 2023. (Noah Berger/AFP via Getty Images)

https://www.theepochtimes.com/americas-biggest-banks-experience-massive-withdrawals_5167584.html 

America’s 25 biggest banks saw a huge $90 billion outflow of deposits last week, a sharp reversal from the prior week where larger financial institutions absorbed some of the deposits being withdrawn at a record pace from smaller banks in the wake of the Silicon Valley Bank (SVB) collapse.

Between the collapse of SVB over March 10 weekend and March 22, domestically chartered  banks in the United States lost a total of roughly $213 billion in deposits as skittish savers rushed to withdraw their money, according to the latest seasonally adjusted Federal Reserve figures on deposit outflows.

But while the first week following the failure of SVB saw a record drop of $196.4 billion in deposits in smaller banks—defined as ones smaller than the top 25 in terms of assets—the latest week saw a reversal.

Small domestically chartered banks saw an increase of roughly $6 billion in the past week. Still, the latest figures show that smaller banks remain down just over $190 billion since the collapse of SVB sent shockwaves across markets.

Big banks, meanwhile, which saw an increase in deposits in the week following the SVB failure, saw a sharp decline last week. Deposits at large domestically chartered banks dropped by $89.7 billion in the week ended March 22. A week prior, big banks gained $67 billion in deposits. The latest data show that large U.S. banks are down $22.7 billion since the SVB collapse.

Money market funds have been among the major beneficiaries of the deposit outflows. Around $286 billion has flooded into U.S. money market funds so far in March, the Financial Times reported, citing EPFR data. That’s the biggest month of inflows since the height of the COVID-19 pandemic in 2020.

The failure of SVB, which had roughly $212 billion in assets for the final quarter of 2022, was the second largest bank collapse in U.S. history.

Credit Crunch Coming?

Following the failure of SVB, a number of emergency measures were rolled out to calm markets, including expanded deposit guarantees and a special swap line at the Fed where banks could borrow under easier terms than normal to meet depositor demand.

While the immediate threat of broader financial contagion seems to have abated, experts warn that the real economy is poised to take a hit as lending standards tighten and credit dries up.

Lending standards started tightening in early 2022 with the Federal Reserve’s inflation-fighting rate hikes and balance-sheet runoff. Now, they’re getting even tighter amid the early fallout from U.S. banking sector turmoil.

“The recent failure of Silicon Valley Bank and Signature Bank, as well as worries about the rest of the banking system (whether justified or not), has contributed to growing credit tightness,” Peter Earle, an economist at the American Institute for Economic Research, told The Epoch Times in an emailed statement.

“The reduction in corporate bond issuance over the past few weeks is a clear sign of that development,” he added.

U.S. companies with the highest credit ratings sold a record $144 billion of debt securities in February to get ahead of further potential interest-rate hikes, according to a recent report from BMO Capital Markets.

But the failure of SVB—and of Signature Bank just days later—led to deals in the corporate bond market grinding to a near standstill. During the week following the twin bank collapses, there were zero investment-grade bond deals priced, according to PitchBook LCD. Although deals started up again the following week, activity remained weak.

The situation was much the same in the high-yield bond market for companies with lower credit ratings, with near-zero issuance over the past several weeks.

Earle said that, if worries about the health of the U.S. banking sector continue, this will “eventually result in lending being unavailable or only accessible at exorbitant rates. And that will constitute a credit crunch.”

During a credit crunch, banks raise their lending standards, making it more difficult for households and businesses to obtain loans.

‘Big Issue for Local Communities’

After an initial surge of $129.3 billion in deposit outflows from all U.S. domestically chartered banks in the first week following the SVB collapse, the run on deposits slowed last week to a net $84 billion.

While U.S. regulators have said this represents a stabilization in deposit outflows, there’s considerable uncertainty as to where things go from here.

“What’s unclear for us is how much of these banking stresses are leading to a widespread credit crunch. That credit crunch … would then slow down the economy. This is something we are monitoring very, very closely,” Neel Kashkari, president of the Federal Reserve Bank of Minneapolis, said in a March 26 interview on CBS.

Kashkari noted that it’s too soon to gauge the “imprint” that bank stress will have on the economy.

Allianz chief economic adviser and noted economist Mohamed El-Erian wrote in a recent op-ed for Bloomberg that if deposit outflow from regional banks continues, this spells trouble.

“This could become a big issue for local communities, regions, and sectors that fear that their access to loans will be curtailed because their traditional banking partners will have to shrink their balance sheets after losing deposits,” he wrote.

El-Erian believes that the bank turmoil will slowly infect the real economy by squeezing access to credit.

“This economic contagion, which will play out over time, threatens to increase the challenges facing an economy that is dealing with inflation, a mishandled interest-rate hiking cycle, declines in personal savings, bouts of financial instability and a slowing global economy.”

Experts have said that small businesses that often rely on local banks for their lending needs are particularly vulnerable to the looming credit crunch.

South Africa Pushes to Delay Coal Plant Closures

Vapour rises from a chimney at the Eskom Holdings SOC Ltd. Tutuka coal-fired power station in Mpumalanga. 

Vapour rises from a chimney at the Eskom Holdings SOC Ltd. Tutuka coal-fired power station in Mpumalanga. Photo by Waldo Swiegers /Photographer: Waldo Swiegers/Bl

https://financialpost.com/pmn/business-pmn/south-africa-pushes-to-delay-coal-plant-closures 

(Bloomberg) — South Africa has told rich countries backing its $8.5 billion energy transition deal that it wants to delay the closure of some units at its coal-fired power plants, people familiar with the situation said. 

With blackouts often exceeding 10 hours a day, the government is under pressure to hold on to whatever generation capacity it has.

The government has yet to make a decision and no formal request has been submitted to its JETP partners, but they are likely to take a pragmatic attitude given the power crisis and political constraints, the people said. They asked not to be identified because of the sensitivity of the talks. 

Unveiled at the COP26 climate conference in Glasgow, the JETP is meant to help South Africa end its dependence on coal and meet its target of reaching net zero carbon emissions by 2050.

Under the agreement, which was formally signed last year, a mix of loans, grants and debt guarantees from Germany, France, the US, UK and the European Union will help South Africa build out renewable alternatives. 

Troubled state power utility Eskom Holdings SOC Ltd. closed the dilapidated Komati plant last year and is due to close another 5 of its 14 remaining coal-fired plants by 2030. 

Vikesh Rajpaul, who runs the Just Energy Transition office at Eskom, said life extensions are not being considered for the aging plants but some units may have to be kept open longer than planned to address the electricity crisis.

“There is an understanding and appreciation for the energy shortage that we have,” he said of talks with JETP partners. 

Vincent Magwenya, a spokesman for the South African presidency, didn’t immediately respond to a text message or answer his phone. The funding partners all said they remain committed to the JETP, without commenting on the possibility of delays.