Sunday, June 7, 2020

Saudis Make Biggest Oil Price Hike in 20 Years After OPEC+ Cuts


https://finance.yahoo.com/news/saudis-biggest-oil-price-hike-171705876.html

(Bloomberg) -- Saudi Arabia made some of the biggest price increases for crude exports in at least two decades, doubling down on its strategy to bolster the oil market after OPEC+ producers extended historic output cuts.

The steepest jump will hit July exports to Asia, state producer Saudi Aramco’s largest regional market, according to a pricing list seen by Bloomberg. Overall, the increases for Saudi crude erase almost all of the discounts the kingdom made during its brief price war with Russia.

The sharp price increases show that Saudi Arabia is using all the tools at its disposal to turn around the oil market after prices plunged into negative territory in April. As the price setter in the Middle East, the increases in its official prices may be followed by other producers.

Tighter crude supply is helping repair an oil market battered by the coronavirus. Unprecedented output cuts led by the Saudis and Russia boosted prices in May, and the OPEC+ group decided Saturday to extend those limits through July. Brent crude, down 36% this year, has clawed back some of its losses and ended trading on Friday at more than $40 a barrel.

But the profits that oil refiners make from processing crude into fuel are struggling to keep up with the rising market, and the sharp Saudi price hikes are likely to exacerbate that problem. Representatives for refineries from Europe and Asia expressed concern and said the pricing would crush margins.

Price War

Saudi Arabia unleashed a price war in March when it slashed official selling prices by the most in three decades. The kingdom took that drastic step after failing to reach an agreement with Russia to extend production cuts in the face of the pandemic’s destruction of oil demand.

After Tweets, phone calls and top-level consultations, OPEC+ returned to negotiations and hammered out the biggest output curbs in history, pledging to take nearly 10 million barrels a day off the market. U.S. production plunged by roughly 2 million barrels daily as low prices drove producers to shut wells.

OPEC+ chose on Saturday to renew production limits at almost the same level, instead of tapering them as planned at the end of June. Aramco, which typically announces pricing on the fifth day of each month, had delayed its July numbers until after OPEC+ members made their decision.

Saudi Arabia sells its crude at a differential to oil benchmarks, announcing every month the discount or premium it’s charging to global refiners. The so-called official selling prices help set the tone in the physical oil market, where actual barrels change hands.

With China’s demand for crude now rising, the Saudis are raising prices. The month-on-month increase in the official selling price for flagship Arab Light crude to Asia, which accounts for more than half of Saudi oil sales, is the largest in at least 20 years. Aramco raised Arab Light to Asia by $6.10 a barrel to a premium of 20 cents over the benchmark.

It raised July pricing for all grades to Asia by between $5.60 and $7.30 a barrel. That compares with an expected increase of about $4 a barrel, according to a Bloomberg survey of eight traders and refiners.

Buyers in the U.S., the Mediterranean region and Northwest Europe will also pay more for oil.
Story Link: Saudis Seek to Bolster Oil Rally With Price Boost as OPEC+ Cuts
For more articles like this, please visit us at bloomberg.com

Subscribe now to stay ahead with the most trusted business news source.

©2020 Bloomberg L.P.

Largest Crude Oil Tanker in the World - Euronav Oceania

Thursday, June 4, 2020

Last oil tanker in Iranian flotilla reaches Venezuela

If the United States goes to war with Iran, you are unlikely to hear the word “oil” uttered by top Trump administration officials, but make no mistake: that three-letter word lies at the root of the present crisis, not to speak of the world’s long-term fate. (Photo: Jorge Guerrero/AFP/Getty Images) 

http://www.tankeroperator.com/ViewNews.aspx?NewsID=11612

The oil tanker ‘Clavel,’ the last of a five-tanker Iranian flotilla, has made it to Venezuela’s shores to deliver much-needed gasoline. 
 
The final delivery comes just three days after the previous cargo arrived.
 
The fifth oil tanker entered Venezuela's’s waters on Sunday, carrying the last shipment of the more than 1.5 million barrels of fuel sent to Venezuela by Iran.
 
Both nations are facing tough US sanctions, with Washington willing to stop the Iranian lifeline that was meant to alleviate fuel shortages in the Latin American country.
 
Earlier this week, Venezuela’s military escorted four other ships--the ‘Fortune,’ the ‘Forest,’ the ‘Faxon’ and the ‘Petunia’--through its exclusive economic zone to their destination. The ‘Faxon’ was the fourth to arrive at Puerto la Cruz on the country’s eastern coast on Friday.
 
Despite Venezuela having vast oil reserves, its refining capacity has been limited, and its energy crisis has only worsened amid sweeping US sanctions. The restrictions dealt a painful blow to the republic’s oil sector, which accounts for most of its budget revenues.

Wednesday, June 3, 2020

Oil falls Below $40 on doubts early OPEC+ meeting will go ahead this week

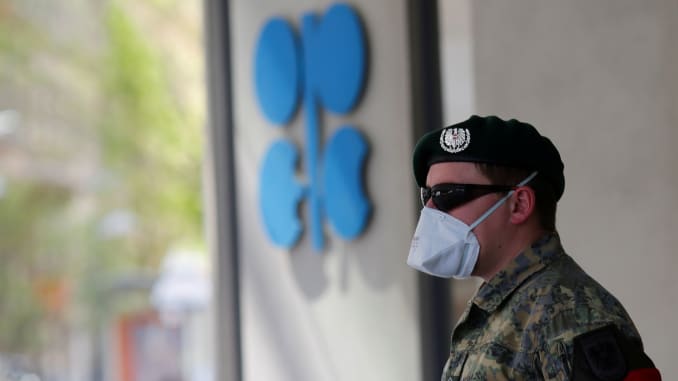
An Austrian army member stands next to the logo of the Organization of the Petroleoum Exporting Countries (OPEC) in front of OPEC's headquarters in Vienna, Austria April 9, 2020.
An Austrian army member stands next to the logo of the Organization of the Petroleoum Exporting Countries (OPEC) in front of OPEC’s headquarters in Vienna, Austria April 9, 2020.
Leonhard Foeger | Reuters

https://www.cnbc.com/2020/06/03/oil-prices-opec-likely-to-extend-deepest-ever-production-cuts-analysts-say.html
  • OPEC and non-OPEC allies, a group of oil producers sometimes referred to as OPEC+, had been expected to hold their next meeting on Thursday.
  • However, while OPEC kingpin Saudi Arabia and non-OPEC leader Russia were thought to have tentatively agreed on a one-month extension to production cuts, S&P Global Platts reported on Wednesday, citing unnamed sources, the date of a meeting to finalize the deal remains uncertain. 
  • Analysts at research firm Eurasia Group believe the upcoming OPEC+ meeting will “probably” see the energy alliance agree to extend the commitment to reduce oil production by 9.7 million b/d from July to September.
Oil prices erased gains on Wednesday, with Brent crude futures falling back below $40 a barrel, on doubts an early meeting of some of the world’s most powerful oil producers will go ahead as planned.
OPEC and non-OPEC allies, a group of oil producers sometimes referred to as OPEC+, had been expected to hold their next meeting on Thursday.

However, while OPEC kingpin Saudi Arabia and non-OPEC leader Russia were thought to have tentatively agreed on a one-month extension to production cuts, S&P Global Platts reported on Wednesday, citing unnamed sources, the date of a meeting to finalize the deal remains uncertain.

OPEC member Algeria, which currently holds the rotating presidency of the group, proposed late last month that the meeting should be brought forward from the original date of June 9-10.

Brent crude futures traded at $38.91 a barrel during Wednesday afternoon deals, down over 1.5%. Earlier in the session, the international benchmark had climbed above the $40-a-barrel mark for the first time since March 6.

Meanwhile, U.S. West Texas Intermediate (WTI) crude futures stood at $36.26, almost 1.6% lower. The contract had also climbed to its highest level since early March earlier in the trading day, but it has since erased those gains.

Oil prices have soared in recent weeks, rebounding from the lows of April amid optimism about an economic recovery in China and as other economies seek to gradually relax lockdown measures.

In April, OPEC+ agreed to cut oil production by a record 9.7 million barrels per day (b/d), approximately 10% of global output. The move was designed to prop up prices as the coronavirus pandemic led to an unprecedented collapse in oil demand.

The production cuts began on May 1 and are set to run through to the end of June. Under the current deal, the cuts will then be tapered back to 7.7 million b/d from July through to the end of 2020, and 5.8 million b/d from January 2021 through to April 2022.

What options are on the table?

Analysts at research firm Eurasia Group believe the OPEC+ meeting will “probably” see the energy alliance agree to extend the commitment to reduce oil production by 9.7 million b/d from July to September.

“As usual, Russia is playing hard to get in the run up to the talks but will prove willing to compromise in the end. Crucially, the Russians will be keen to reach a common position with the Saudis to demonstrate that the OPEC+ partnership remains firm,” analysts at Eurasia Group said in a research note.

“As for the Saudis, a short-term extension is an acceptable option given that there will probably be room to revisit cuts based on developments in markets,” they added.

Unlike the March meeting ahead of the Saudi-Russia price war, analysts believe the mood among key members of the energy alliance is now much more positive, with leaders of all the main oil producers aligned on the need to continue cooperation.

A deal to extend the current level of OPEC+ cuts through to the end of 2020 is also thought to be possible, although significantly less likely than a two- or three-month extension.

Uptrend in oil prices will ‘not last’

Tamas Varga, senior analyst at PVM Oil Associates, said those hoping for oil prices to climb above $50 a barrel will most likely have to wait until the latter part of 2021.

“We have long argued that the uptrend we have been seeing in the oil market and which started at the end of April would not last,” Varga said.

He argued that investors were viewing the current race to pre-pandemic economic activity “as a sprint,” whereas, in reality, “it is at least a half marathon.”

“This is not to say that prices will not go higher in the immediate future,” Varga said, particularly given the market optimism that is primarily based on a significant reduction in both OPEC and non-OPEC supplies.

The International Energy Agency warned late last month that the coronavirus crisis had set in motion the largest drop in global energy investment history, with spending set to plunge in every major sector this year.

It warned the economic impact of the crisis could have “serious” implications for energy security and clean energy transitions.

Monday, June 1, 2020

Why Cushing Matters – A Look at the WTI Benchmark

This photograph taken in August shows progress contractors are making in building Keyera's Wildhorse Terminal at the Cushing terminal. The tanks, which will have a total capacity of about 4 million barrels, are expected to be in service by the middle of next year. [PROVIDED BY GENSCAPE] 
 This photograph taken in August 2019 shows progress contractors are making in building Keyera's Wildhorse Terminal at the Cushing terminal. The tanks, which will have a total capacity of about 4 million barrels, are expected to be in service by the middle of next year. [PROVIDED BY GENSCAPE]

In response to the drastic decrease in global demand and over-supply due to the COVID-19 pandemic and the recent OPEC+ meetings in March 2020, the oil market has endured extreme stress, particularly related to logistics, storage, and finance.

With the demand collapse and refinery utilization rates near record lows, storage utilization levels have risen dramatically. The arbitrage price signals have responded to volatile market fundamentals to re-direct barrels to flow into storage due to the declining exports in the US Gulf Coast market.

Consequently, the stress in the oil market is reflected in the price signals from the NYMEX Light Sweet Crude Oil futures contract (also called “WTI futures”), which is based on physical delivery of WTI-type crude oil at the Cushing hub. The physical-delivery requirement of WTI futures is a direct link to the underlying physical market. At futures expiration, the exchange matches the buyers and sellers who elect to make or take delivery of physical oil. As a result of the recent extreme market imbalances between demand (low refinery runs) and supply (rising stocks), the day prior to expiration of the May 2020 WTI futures contract led to negative oil prices as buyers and sellers liquidated their futures positions. Negative prices can occur in commodity markets during times of oversupply and low demand, and these market conditions led to unprecedented price action in the May 2020 WTI futures contract. 

A regulated futures contract provides each buyer and seller with access to the clearinghouse and a financial guarantee for their trades. Despite the extreme market conditions, WTI futures ultimately provided for convergence between the futures and cash markets and performed its critical function as the central clearing mechanism for buyers and sellers in the crude oil market. This paper provides further information on the strengths of Cushing as both a trading and storage hub, most notably its pipeline connectivity, storage logistics, and price discovery role as a global benchmark. All of these strengths will be key as market participants hedge price risk while storage utilization levels rise.

Overview of Cushing logistics

At the heart of the global pricing network, the Cushing hub provides the physical delivery mechanism for the CME Group’s Light Sweet Crude Oil Futures contract. At the time when the WTI futures contract was first listed in 1983, Cushing was a vibrant hub for cash market trading of crude oil with a network of pipelines, refineries, and storage terminals. Today, Cushing is the key nexus of market fundamentals for the global crude oil market, with nearly two dozen pipelines and 20 storage terminals.

According to the EIA, the working storage capacity in Cushing is 76 million barrels, and 91 million barrels of total shell capacity as of September 2019. Currently, the shell capacity in Cushing is approaching 100 million barrels in the second quarter of 2020. The EIA defines the “working storage capacity” and “net available shell capacity” for Cushing and by PADD district.1 Generally, the working storage capacity accounts for around 85% of the nameplate shell capacity of a tank, given that each storage tank has a roof and a heel that have to be managed by the terminal operator, and they typically are not able to use the full 100% shell capacity.

The pipeline infrastructure in the Cushing market is expansive, with approximately 3.7 million b/d of inflow pipeline capacity to Cushing and 3.1 million barrels per day of outflow capacity. The in-bound pipelines deliver crude oil streams produced in Canada and the US shale oil areas, including the Bakken, Niobrara, and Permian producing areas. The out-bound pipelines supply crude oil to the main refining centers in PADDs 2 and 3.

It is not just the storage or pipeline capacity that make Cushing the critical hub as the delivery point for the global oil benchmark, but also the interconnectivity between a diverse mix of operators at Cushing. The WTI Futures contract allows for delivery through Enterprise or Enbridge facilities in Cushing or at a facility that is connected to either. The Enterprise terminal provides a key junction point in Cushing, capable of facilitating the transfer of tens of millions of barrels of crude oil every month. A firm that elects to take delivery after the termination of the WTI futures must have storage and/or pipeline capacity connected to one of the NYMEX delivery locations in Cushing. From there, the firm can elect to take the oil into storage or into a pipeline with connectivity to PADD 2 refineries and to the Gulf Coast.

The physical-delivery requirement of WTI futures provides a direct link to the underlying physical market, and futures also provide the security of a financially-guaranteed clearinghouse for buyers and sellers. Further, Cushing terminal operators require firms to submit nominations for crude oil flows ahead of the delivery cycle in order to ensure the deliveries scheduled on and off exchange flow unencumbered.

Overview of Market Conditions

The unprecedented global market fundamentals have put intense stress on the oil industry in the first half of 2020, as companies respond to the volatile arbitrage price signals and hedge the price risk associated with demand destruction and rising stocks of crude oil.

The first indicator of the energy demand destruction from COVID-19 in the United States was seen in the New York Harbor RBOB gasoline futures contract (“RBOB futures”). The futures market for RBOB Gasoline forecasted demand concerns early when prices traded at a 20-year low of $0.376 on March 23, 2020. RBOB futures is an important indicator for global gasoline as it is the only gasoline futures contract to trade electronically around the clock. In the first quarter of 2020, RBOB futures has averaged 230,000 contracts traded per day with 380,000 contracts in open interest on April 23, 2020.

The impact on gasoline was more immediate due to the timing of the Coronavirus outbreak. Historically, gasoline stocks build in the winter in anticipation of the peak summer driving demand. As it became apparent that the summer driving season would be significantly curtailed, flat price RBOB futures prices started to decline at a faster pace than crude oil prices, which is reflected in the crack spread chart below.

In response to the sharp drop in gasoline prices, the oil refining companies were quick to respond to the price signals, as is evident in the decline in the US refinery utilization rate, which dropped to lows last seen in 2008 after the Lehman financial crisis.

Crude oil production however was not curtailed at the same pace as the reduction in refinery runs. This led to an increase in storage demand as market participants moved barrels into storage. With the over-supply coupled with demand collapse on a global scale, the price arbitrage was not favorable for crude oil exports. Exports have become a major outlet for US crude oil, which enabled US crude to become the marginal barrel of supply in the global energy markets.

One of the first price signals of oversupply of crude oil was the rapid price decline in US domestic crude oil cash markets. By late March 2020, WTI Midland and WTI Houston were trading at widening discounts to the WTI futures benchmark, providing an early indicator that there were supply and demand imbalances in the US crude oil market. This price arbitrage led market participants to direct barrels to flow into storage at Cushing. The chart below shows the general price volatility of the US domestic crude oil grades during the March and April 2020 timeframe. Ultimately, WTI futures provided for convergence between the futures and cash markets at expiry on April 21, 2020.

CME Group has a useful trading tool on its website, called Pace of the Roll, which tracks the daily roll activity taking place in Energy futures products to help analyze the progression of open interest in key benchmark contracts, including WTI futures. The chart below depicts the CME Group’s QuikStrike Pace of the Roll tool on April 17, 2020, which was three trading days before the expiration of the May 2020 WTI futures contract. This chart shows that the open interest positions were higher than average as shown by the orange line. Given the unprecedented global market fundamentals, firms relied more heavily on the WTI futures contract to manage price and counterparty risk.

At futures expiration, CME Group matches the buyers and sellers who elect to make or take delivery of physical oil. As a result of the recent extreme market imbalances between demand (low refinery runs) and supply (rising stocks), the expiration of the May 2020 WTI futures contract led to negative oil prices as buyers and sellers had to settle their futures positions. It is also important to note that after trading negative on both the afternoon of April 20 and the morning of April 21, the May WTI contract ended up with a final settlement price of $10.01, reflecting the successful convergence of futures and cash prices at final settlement. Trading was not interrupted, allowing the market to continue the process of price discovery.

Looking Ahead

It is important to note that CME Group futures markets worked as designed. Our futures prices reflected fundamentals in the physical crude oil market driven by the unprecedented global impacts of the COVID-19 pandemic, including decreased demand for crude, global oversupply, and high levels of US storage utilization. After advance notice to our regulator and the marketplace in early April 2020, CME Group accommodated negative WTI futures prices on April 20 so that clients could manage their risk amid dramatic price moves, while also ensuring the convergence of futures and cash prices. In the end, WTI futures performed its critical function as the central clearing mechanism for buyers and sellers in the crude oil market, and provided a transparent, fair, and robust benchmark price.

Going forward, the unprecedented global market fundamentals will continue to put intense stress on the oil industry in 2020, as companies respond to the volatile arbitrage price signals and hedge the price risk associated with the rising level of crude oil inventories.