Corpus
Christi Authority Port Authority has announced several milestones in the
development of the crude oil export terminal on Harbor Island, Texas.
Locally-based Lone Star Ports will lead the development of the
terminal, claimed to be the first US onshore export terminal able to
handle fully-laden VLCCs.
Lone Star is a joint venture between The Carlyle Group and The Berry
Group. Berry is the largest private employer in the Corpus Christi area
through its numerous investments and operations in the oil and gas
industry and its subsidiary Bay Ltd, a Corpus Christi-based
infrastructure, construction, and fabrication contractor for the oil and
gas sector.
Lone Star Ports is led by CEO Jeremiah "Jerry" Ashcroft III who has
been responsible for the development of several large marine terminals.
The company has signed indicative agreements with Harvest Midstream and
EPIC Crude Pipeline, which is backed by funds affiliated with Ares
Management. These two pipelines will provide connectivity to more than
one million barrels per day.
It also entered into an indicative agreement with Martin Midstream
Partners to provide a single, integrated VLCC solution on Harbor Island.
These agreements and arrangements still remain subject to definitive
documentation among the relevant parties, co-ordination with the Port,
satisfactory completion of due diligence and final approval by each
relevant party.
"Our partnership with the Carlyle Group is designed to assure global
energy markets that requisite infrastructure will be in place and
ready to support the growing exports of American crude oil. We are
pleased with the progress The Carlyle Group has achieved thus far in
reaching full project commercialisation," said Sean Strawbridge, Port of
Corpus Christi CEO.
HOUSTON
— Oil prices tumbled more than 7 percent on Tuesday, falling to their
lowest levels in more than a year, after investors learned that Russia
and the United States were pumping a lot more oil than had been
expected.
The American benchmark fell
below $47 a barrel for the first time in 15 months, capping a slide
that has brought prices down by more than a third since early October.
Bountiful,
cheap oil supplies are an unanticipated holiday bonus for American
consumers. The average price of regular gasoline has fallen to $2.37 a
gallon, according to the AAA motor club, 26 cents lower than a month
ago. For most of the year gasoline prices were rising, but the recent
decline in oil prices has driven gasoline down by about a nickel a
gallon compared with a year ago.
Oil
prices had stabilized earlier this month when the Organization of the
Petroleum Exporting Countries and Russia agreed to slash production by
1.2 million barrels a day. But Russia announced on Monday that its
output had increased to more than 11.4 million barrels a day, a record,
putting in doubt its commitment to coordinate policies with Saudi Arabia
and other oil producers.
On
the same day, the Energy Department reported that the United States was
producing 11.6 million barrels of crude oil a day, nearly a million
barrels more than a year ago. The department projects that shale-oil
production will climb to record levels this month, and increase by
134,000 barrels a day in January.
A
shortage of pipelines has driven down oil prices from the Permian Basin
of West Texas and New Mexico, the most productive American oil field.
But the completion of a series of pipelines in late 2019 should benefit
producers and increase exports, adding even more barrels to the global
glut.
The
oil industry has struggled since prices plummeted to below $30 a barrel
in 2016. Hundreds of small producers and oil-services companies sought
bankruptcy protection, and more than 160,000 jobs were cut. As prices
increased in 2017 and earlier this year, the industry regained some of
that lost ground — a recovery now under threat.
“It
sure will hurt if it lasts very long,” said Tom Dunlap, president of
Tripledee Drilling of Ardmore, Okla. Mr. Dunlap said a price of $60 to
$70 a barrel was typically needed to drill a new well profitably in his
state.
Oil companies have become more
efficient by relying on robotics and other technologies to replace
workers, enabling them to explore and produce at lower prices. Those
adjustments could come in handy as businesses are forced to cut back
again in the coming months.
“These
organizations have had to figure out they need to make a profit at $50
to $60 oil,” said Thomas M. Siebel, chief executive of C3, an
artificial-intelligence software company that works with Royal Dutch
Shell. “To do that they need to lower the cost of production, lower
their exploration costs, lower their drilling costs; costs of operation
have to be more efficient.”
So far,
there are few signs that companies will meaningfully reduce exploration
in 2019, though that could change if prices keep falling and the economy
slows.
A version of this article appears in print on , on Page B2 of the New York edition with the headline: Oil Prices Plummet 7% As Investors Fear a Glut.
OPEC has its work cut out to persuade the market that its output caps
will stabilize oil prices -- and U.S. producers aren’t helping.
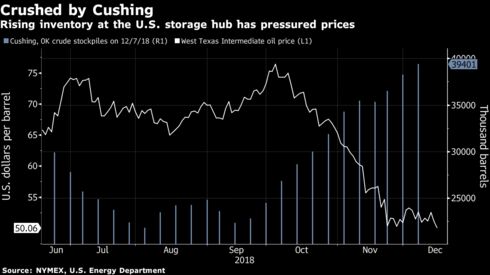
Crude
settled below $50 a barrel in New York on Monday for the first time in
more than a year and continued falling in after-hours trading. The slide
began after data provider Genscape Inc. was said to report growing
inventories at the biggest American storage hub and intensified as the
U.S. Energy Department forecast higher output in the country’s shale plays.
Oil prices are on track for a third straight monthly decline
despite efforts by OPEC, Russia and other major exporters to halt the
slide. Crude had slunk near $50 in recent weeks but always rebounded.
Crossing the threshold was “significant," said Michael Loewen, a
commodities strategist at Scotiabank in Toronto.
“We’re probably going to see a supply slowdown in the U.S.," he said by telephone. “I do think that producers will react."
A dive
for U.S. equities added to the pressure on Monday. The S&P 500 hit a
14-month low as investors anticipated a Federal Reserve interest-rate
hike that could slow the economy.
West
Texas Intermediate for January delivery fell $1.32 to settle at $49.88 a
barrel on the New York Mercantile Exchange. Bears gained steam after
the official close, with oil falling to $49.01, the lowest level since
September 2017. The WTI February contract fell to $49.47.
Brent
for February settlement closed down 67 cents to $59.61 on London’s ICE
Futures Europe exchange. The global benchmark traded at a premium of
$9.41 a barrel to same-month WTI.
“There’s always a question mark over to what extent the OPEC
countries and Russia will or will not fulfill their promises,” said
Pavel Molchanov, a Raymond James & Associates Inc. analyst. “There
is naturally some skepticism.”
It typically takes about six weeks
for OPEC nations to implement supply changes, and Saudi Arabia, the
group’s biggest producer, faces added political pressure from U.S.
President Donald Trump to keep the taps open, Molchanov said.
Other oil-market news:
Gasoline futures fell 1.7 percent to $1.4104 a gallon in New York trading.
A
former lobbyist who’s helped drive the Trump administration’s policies
to expand drilling on public lands is poised to take over at the U.S. Interior Department.
Kuwaiti Oil Minister Bakheet
Al-Rashidi and two top executives of state-owned energy companies
resigned in the latest sign of disputes within OPEC’s fifth-biggest
producer.
— With assistance by Catherine Ngai, and Rakteem Katakey
The oil producer’s group has been seriously weakened by its need to bring an outsider into its heart to broker a deal on output.
If anyone doubted that OPEC is nowlittle more than a zombie organization, the last 10 days have proved it.
The
group has shown itself incapable of making it own decisions. Its
smaller members have borne the brunt of an agreement to cut output that
was only achieved after Russia took control of discussions from the
heart of OPEC’s head office. Then, even after Saudi Arabia announced it
would reduce supply by nearly a million barrels a day by January, oil
traders merely shrugged.
It is a sad result for an organization that once made governments tremble. Here’s how it unfolded.
OPEC oil ministers gathered in the group’s secretariat
building on a wintry Thursday in Vienna. Weakening demand growth and
soaring U.S. production prompted agreement that they needed to reduce
production in order to balance the market in 2019. What they didn’t see
eye to eye on was how to share that burden.
Saudi Arabia insisted that all members should play
an equal part, cutting by the same percentage from a new baseline set
at October’s production level. Naysayers argued that, given how the
group’s biggest producer had boosted its own output by more than a
million barrels a day since May, it should therefore bear the brunt of
the cuts needed to get the market back into balance. Furthermore, Iran
led a contingent of countries claiming their special circumstances
warranted exemptions.
The stand-off looked very similar to the one that had scuppered a deal in Doha
in April 2016 – something that nobody wanted to repeat. But by the end
of that Thursday, Dec. 6, officials had failed to reach an agreement and
Saudi oil minister Khalid Al-Falih said he was “not confident” one was
possible. The gala dinner at the Liechtenstein Palace was sparsely
attended, with both the Saudi and Iranian delegations, among others,
skipping the event.
Friday, the day originally scheduled for the
group to meet with its partners, began little better. OPEC ministers
were once again locked away in discussions. The talks went nowhere, and
the OPEC+ meeting got pushed back to the afternoon.
Then the Russians arrived.
Bilateral
discussions to hammer out negotiating positions are a regular feature
of the days and hours before the main OPEC gatherings. They take place
in the suites of Vienna’s grandest hotels, where the various delegations
are holed up. In recent years, the Russians have been part of this
scene.
But when Russian Energy Minister Alexander Novak arrived
Friday morning, he moved in to the office of OPEC’s Secretary General.
If ever there was a symbol of OPEC’s demise, it was this. He then
summoned first Iran’s oil minister, then Saudi Arabia’s, for about 45
minutes each. Two hours later, the group reached a deal. And Iran, Libya
and Venezuela got their exemptions, even if they didn’t appear in the
final communiqué.
The agreement that emerged is, on paper, fair
and reasonable. OPEC will cut production by 800,000 barrels a day from a
new baseline of October 2018 production, with participating members
cutting by 3 percent. The group’s partners will reduce their supply by 2
percent, contributing a further 400,000 barrels a day. That combined
reduction is just about enough to balance supply and demand in the first half of next year.
Saudi
Arabia went even further. Al-Falih said the kingdom’s production would
fall to 10.2 million barrels a day in January, down from 11.1 million
last month.
That looks like a huge cut, but it is still 150,000 barrels a day above its target under the original deal.
And
this is where the inequality of the new OPEC+ deal becomes apparent.
Saudi Arabia, Russia, the United Arab Emirates and Iraq boosted their
combined output by almost 1.6 million barrels a day between May and
October. That not only contributes to the current glut, it also gives
them much higher starting points for the latest cuts than for the
previous ones. Other OPEC members all face lower starting points.
The effect has been to shift a disproportionate
share of the burden of OPEC’s supply management since 2016 onto the
group’s smaller producers.
Handing control of OPEC decision making to the Kremlin has
come at a high cost for the group, and most particularly for its smaller
members. Some of the latter were already feeling marginalized. This
latest deal will do nothing to change their view and the divisions
between the organization’s “haves” and “have nots” will only widen.
Russia
has done very well out of this. It agreed to cut output by 230,000
barrels a day from its October output level of 11.42 million. That would
reduce its production to 11.19 million barrels a day, a figure that is
just 15,000 barrels below its original 2016 baseline — a cut of just 0.1
percent.
Contrast that with OPEC member Algeria, which produces around
a tenth as much oil as Russia. Its new target will be 1.023 million
barrels a day. That’s a cut of 66,000 barrels a day, or 6.1 percent
below the 2016 baseline.
And what did this all achieve?
Oil markets have reacted with indifference.
After a brief rally when the deal was revealed, Brent subsequently sank
back below the level it was trading at before the meeting began. Perhaps
traders don’t believe the group will be able to implement the
arrangement, or are waiting to see evidence that it’s taken effect.
OPEC has lost a lot for very little gain.
This column does not necessarily reflect the opinion of the editorial board or Bloomberg LP and its owners.
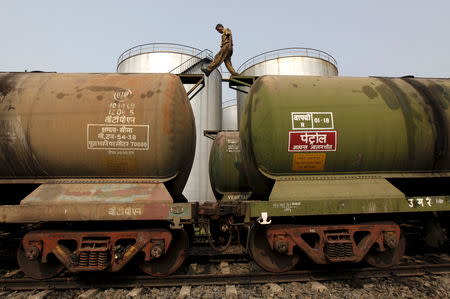
A worker walks atop a tanker wagon to check the freight level at an oil
terminal on the outskirts of Kolkata in this November 27, 2013 file
photo. REUTERS/Rupak De Chowdhuri/Files
NEW DELHI (Reuters) - India's monthly oil imports from Iran plunged
to their lowest in a year in November with Tehran dropping two places to
become only the sixth biggest supplier after New Delhi cut purchases
due to the impact of U.S. sanctions, according to ship tracking data and
industry sources.
Last month, the United States introduced tough sanctions aimed at
crippling Iran's oil revenue-dependent economy. Washington did, though,
give a six-month waiver from sanctions to eight nations, including
India, and allowed them to import some Iranian oil.
India is restricted to buying 1.25 million tonnes per month, or about 300,000 barrels per day (bpd).
In November, India imported about 276,000 bpd of Iranian oil, a
decline of about 41 percent from October and about 4 percent more than
the year-ago month, ship tracking data obtained from shipping and trade
sources showed.
After abandoning the 2015 Iran nuclear deal, U.S. President Donald
Trump is trying to force Tehran to quash not only its nuclear ambitions
and its ballistic missile programme but its support for militant proxies
in Syria, Yemen, Lebanon and other parts of the Middle East.
India's imports from Iran in November, included some parcels that
were loaded in October. In November, Iraq and Saudi Arabia continued to
be the top two oil sellers to India.
The UAE, which was the sixth biggest oil seller to India in October,
became the third top seller to India in November, knocking down
Venezuela by a notch to fourth position.
Nigeria continued at No. 5 position, while Iran slipped to sixth place.
"Iran do not have vessels to export oil on time ... some November
loading vessels will arrive in December," said an industry source, with
knowledge of the matter.
Local and international shippers are not carrying Iranian cargoes
despite India winning a waiver, this source said. The key problem is
that while India can import Iranian oil without falling foul of
Washington, that may not apply to a shipping company signing a new
delivery contract.
Instead, India is relying on Iranian tankers for crude imports and Iran is using many of its vessels for crude storage.
The sources declined to be identified citing the confidentiality of the numbers.
Indian refiners, wary of the impact of U.S. sanctions, had boosted
imports from Iran ahead of their introduction, with imports averaging
about 563,000 bpd in April-November, a growth of about 32 percent from a
low base in the previous fiscal year, the data showed.
In the previous financial year to March 2018 India had cut oil
imports from Iran due to a dispute over development rights of a giant
gas field.
Iran was hoping to sell more than 500,000 bpd of oil to India in
2018/19, its oil minister Bijan Zanganeh said in February, and had
offered almost free shipping and an extended credit period to boost
sales to India.
Government sources say Reuters' calculations showing India's oil
imports from Iran in this fiscal year would be higher than the 452,000
bpd, or 22.6 million tonnes, it imported in the previous year, are
correct.
During January-November this year India's oil imports from Iran rose by an annual 18.4 percent to 552,000 bpd, the data showed.
(Reporting by Nidhi Verma; Edited by Martin Howell and David Evans)


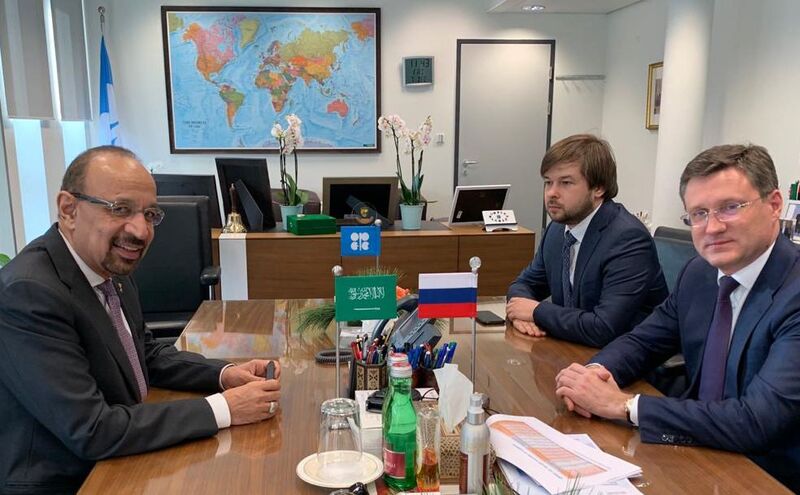 Khalid Al-Falih hands Alexander Novak the keys to OPEC decision making in the office of the group’s secretary general.